

Hundreds of billions in AI infrastructure financing now flows through circular deals where customers are suppliers, suppliers are investors, and all roads lead to OpenAI. The greatest risk isn’t that AI fails—it’s that the technology succeeds while the single company everyone has backed fails to build a defensible moat, triggering contagion that strands capital and stalls the buildout before the transformation completes. You can be bullish on AI and bearish on this financial architecture. They’re separable propositions.
The past month has witnessed a series of deals so circular, so concentrated, and so unprecedented in scale that they’ve transformed the AI boom from a technology story into a financial stability question.
At the center sits OpenAI. Not just as a symbol of artificial intelligence’s potential, but as the potential single point of failure in a system where hundreds of billions of capital are flowing through self-reinforcing loops.
I argued three weeks ago in my analysis of AI valuation dynamics that the bubble debate may have some valid short-term points but also misses part of the long-term view. But those discussions are separate from these recent developments.
What we’re witnessing now is the emergence of a circular financing architecture that is so brazenly shocking to many that it has gone beyond the realm of mere critique into spawning memes.
The actors involved in this capital carousel seem to have justified these deals by conflating two distinct beliefs:
The first is robust: AI represents a structural economic shift comparable to railroads or the internet. Here, I agree.
The second is fragile: OpenAI possesses a durable moat that will capture the lion’s share of this revolution’s value. Here, well, let’s just say I have my doubts.
In recent months, there has been much handwringing over reports of AI’s ROI, or runaway valuations, or costs of infrastructure, or other various existential fears that have raised doubts about whether AI will deliver on the hype to justify the investment.
However, it’s possible we might not get to find out. Because the greatest risk is not that the technology fails or that the value is not realized. It’s that the single company everyone has backed fails to justify the capital flowing through it, triggering a contagion that stalls the buildout of critical infrastructure and strands trillions in investment before the transformation even completes.
What Is Circular Financing in AI?
Map these relationships and a pattern emerges: customers are suppliers, suppliers are investors, investors are customers. The same entities occupy every role simultaneously. Capital flows in circles, making it nearly impossible to distinguish genuine demand from financial engineering.
Consider the deals announced over the past 30 days:
Broadcom and OpenAI formalized their partnership on Monday to jointly build and deploy 10 gigawatts of custom AI accelerators, marking a major expansion of their 18-month collaboration and sending Broadcom shares up nearly 10%.
Nvidia intends to invest up to $100 billion in OpenAI through non-voting shares while simultaneously supplying at least 10 GW of GPU systems.
OpenAI will use Nvidia’s capital to purchase Nvidia’s chips—a portion of the investment literally returns to its source.
AMD will supply hundreds of thousands of MI450 GPUs and build dedicated gigawatt-scale facilities. In exchange, OpenAI receives an option to acquire 160 million AMD shares at one cent each—approximately 10% of the company—potentially generating over $100 billion in revenue for AMD across four years.
Oracle’s rumored $300 billion “Stargate” deal promises 4.5 GW of data center capacity over five years. To deliver this, Oracle plans to purchase roughly 400,000 Nvidia Blackwell chips worth $40 billion. Oracle’s shares surged 40% on the announcement despite no formal filing.
Meanwhile, Nvidia holds an equity stake in CoreWeave, the cloud startup from which Microsoft—OpenAI’s largest investor and Azure provider—rents AI infrastructure to support OpenAI’s compute needs.
This is vendor financing with equity kickers, creating cross-dependencies that obscure true economic value.
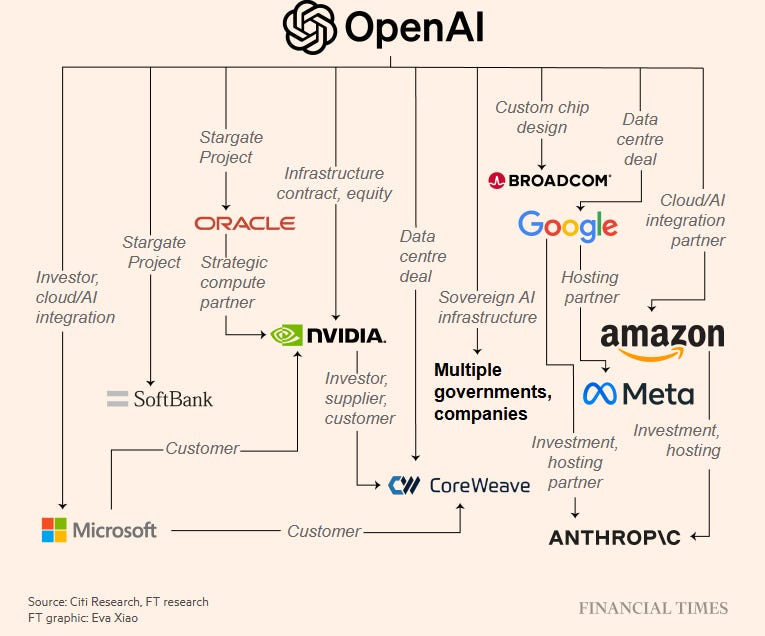
Beyond recent headline deals, Nvidia, CoreWeave, and some of the actors involved also invest in AI startups. Big Tech’s relationships with Anthropic mirror aspects of this structure. But OpenAI remains the loudest signal, the clearest epicenter. Everything flows through Sam Altman’s company, making it the keystone upon which the entire structure depends.