

OpenAI’s record-setting $110 billion funding round is packed full of revelations about the investors who hedged, the losses that necessitated it, and the competitive shift that threatens it. These looming risks are about more than one company. It’s about the fragility now embedded in the financial architecture of the entire AI economy.
Last October, I published an analysis titled “King Sam and AI Circularity.”
The argument was that hundreds of billions of dollars in AI infrastructure financing were flowing through circular deals where customers are suppliers, suppliers are investors, and all roads lead to OpenAI. The greatest risk, I wrote, was not that AI fails, but that the single company everyone had backed would fail to build a defensible moat, triggering contagion that strands capital and stalls the buildout before the transformation completes.
“You can be bullish on AI and bearish on this financial architecture,” I argued. “They’re separable propositions.”
Five months later, that financial architecture has been stress-tested. It has shown cracks in places I did not expect.
On Thursday last week:
NVIDIA reported the largest, cleanest earnings beat in semiconductor history. The stock fell 5.5%. The numbers were perfect, but the reaction was not about Nvidia itself, but about Nvidia as a symbol of the “AI trade”, about the huge AI CapEx numbers (from Nvidia’s customers), and whether the revenues would show up in a timeframe compatible with public markets’ expectations.
CoreWeave, the GPU cloud company at the center of the AI infrastructure buildout, reported revenue growth of 168%. The stock crashed 18.5%.
OpenAI announced $110 billion in new capital at a valuation north of $730 billion. It is the largest private funding round in history. It is also a very high valuation: at $13 billion in revenue in 2025, that is ~56x revenue. Anthropic’s latest valuation at ~27x pales in comparison.
Record performance. Record sell-offs. Record capital raise.
These are not three separate stories. They are one story. It is a story about what happens when the financial architecture built for one paradigm - a training-compute monopoly - collides with the emergence of another: an inference-compute oligopoly where the positions are not established, the moats are shallow, and the company at the center of the web projects $218 billion in cash burn before turning a profit.
What makes this moment different is not the scale of the numbers. Silicon Valley has seen large rounds before. It has seen bubbles before. What it has not seen is a single private company sit at the center of a capital web this large, one that links sovereign wealth, hyperscalers, chipmakers, leveraged cloud intermediaries, and public equity markets into a single interdependent system.
The AI boom is no longer a collection of startup bets. It is a coordinated financial architecture.
When capital structures become architectures, fragility changes form. Risk is no longer isolated to the failure of an individual company; it becomes systemic because cash flows, contracts, and balance sheets are braided together. The question is no longer whether OpenAI can build better models. It is whether the structure built around it can withstand a shift in the underlying economics of compute.
That shift is now underway.
In my “Two Tales of Compute” series, I drew a sharp line between training compute and inference compute. Training is the capex: massive, synchronized GPU clusters running for weeks to produce a model. Inference is the Opex: the per-query, per-token cost of serving that model to users, billions of times daily.
Training is where the arms race lives. Inference is where the economics resolve.
This distinction always mattered. After this week, it is the only distinction that matters.
To understand what this week actually revealed, we have to trace the capital flows, follow the compute, and decode the shifting economics beneath them.
The $110 billion round nobody fully backed
The OpenAI round reveals more than suggested on the surface.
On Thursday, OpenAI announced it had raised $110 billion at a valuation north of $730 billion. The headline was triumphant. The details were not.
NVIDIA’s contribution landed at $30 billion. That figure requires context.
In September 2025, NVIDIA signed a letter of intent to invest up to $100 billion in OpenAI, contingent on deploying 10 gigawatts of NVIDIA systems. It was the centerpiece of a relationship that appeared to define the AI era: the dominant chipmaker backing the dominant model provider, each reinforcing the other.
By January, the Wall Street Journal reported the deal had “stalled.” NVIDIA CEO Jensen Huang told people privately that it had never been binding. He criticized what he called a lack of discipline in OpenAI’s business approach and voiced concerns about the competitive threat posed by Google and Anthropic. In early February, he confirmed publicly that $100 billion “was never a commitment“ and that Nvidia would “invest one step at a time.”
The $30 billion investment represents a 70% retreat. It arrived alongside a $10 billion NVIDIA investment in Anthropic and $2 billion in CoreWeave. The message was unmistakable: NVIDIA is diversifying away from a single-counterparty bet on OpenAI.
Amazon committed $50 billion, the largest investment it has ever made in any company. But only $15 billion is upfront. The remaining $35 billion is contingent on milestones that, per The Information, are tied to OpenAI either achieving artificial general intelligence or completing an IPO.
The single largest commitment in the largest private round in history hinges on a scientific breakthrough that no one can define, and for which no one can provide a comfortable timeline.
Microsoft, which has been OpenAI’s anchor financial supporter since 2019 with over $13 billion committed across multiple rounds, did not participate.
Three of the entities that understand OpenAI’s economics most intimately each sent a different signal, and none of them was unqualified confidence.
What makes this harder to dismiss is the other side of the ledger.
NVIDIA and Amazon are not merely investors in OpenAI. They are among its largest commercial partners. As part of the Amazon deal, OpenAI’s total AWS commitment expanded to approximately $138 billion over eight years, making it one of Amazon’s single largest cloud customers. William Blair estimated the arrangement could deliver roughly $17 billion annually to AWS, about 11% of its expected 2026 revenue. NVIDIA, of course, sells OpenAI the GPUs it consumes at an industrial scale.
These are not arm-length transactions. They are circular flows where investors are also suppliers, suppliers are also customers, and capital moves in loops that make it genuinely difficult to separate commercial demand from financial engineering. Both companies had powerful strategic reasons to participate in this round, with little to do with OpenAI’s intrinsic value as an investment.
Even so, both hedged.
I want to be very clear about something. I do not question OpenAI’s performance as a model provider. Codex, its multi-agent software engineering platform, has reached over a million weekly active developers and represents real product-market fit. The GPT-5.x frontier series achieves state-of-the-art results across multiple professional benchmarks. OpenAI Frontier, the enterprise agent platform now distributed exclusively through AWS, is a strategically smart move.
These are serious products from a serious technical organization.
But OpenAI’s own financial projections tell a specific story about where the money comes from. And it is overwhelmingly a consumer story.
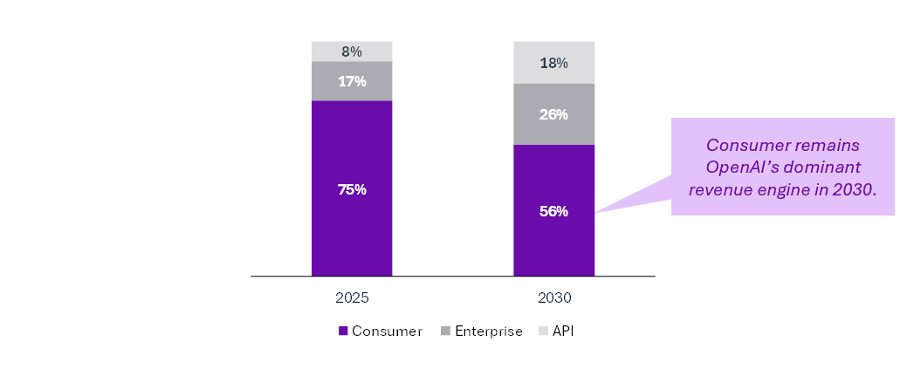
In 2025, ChatGPT subscriptions generated roughly 75% of the company’s $13.1 billion in revenue. Enterprise contributed approximately $2 billion. API revenue crossed $1 billion. By 2030, OpenAI projects consumer revenue at around $150 billion — still over half the total - with enterprise at $70 billion and API at $47.5 billion.
At every point in the forecast, consumer revenue remains the dominant engine.
The monetization strategy for that consumer base now rests substantially on advertising. Sam Altman called advertising a “last resort“ as recently as May 2024. By January 2026, OpenAI was testing targeted ads in ChatGPT for users on its free and Go tiers. Internal projections show $1 billion from ad monetization this year, scaling to $25 billion by 2029.
These are ambitious numbers for a model that no AI company has proven works. Google, which generates over $200 billion annually from an advertising business built over two decades of infrastructure, only announced plans to bring ads to Gemini this year. That validates the direction, perhaps, but also creates formidable competition.
Anthropic went the opposite way entirely, running a Super Bowl ad promising that Claude would remain ad-free.
Meanwhile, ChatGPT’s market share has declined from 86.7% in January 2025 to roughly 64.5% by early 2026. Google Gemini’s monthly active users grew 30% over the August-to-November period while ChatGPT’s grew 6%. Altman issued an internal “code red” memo in December, urging staff to improve the product in response to Google’s advance. The roughly 900 million weekly active users provide scale, but engagement is shallow: 80% sent fewer than 1,000 messages all year.
Strong products. Serious competition. A consumer-heavy revenue mix dependent on unproven monetization. And against that backdrop, a cost structure that defies historical comparison.
$218 billion before breakeven
OpenAI’s latest internal projections, reported by The Information in February 2026, describe a loss trajectory unlike anything in startup history.
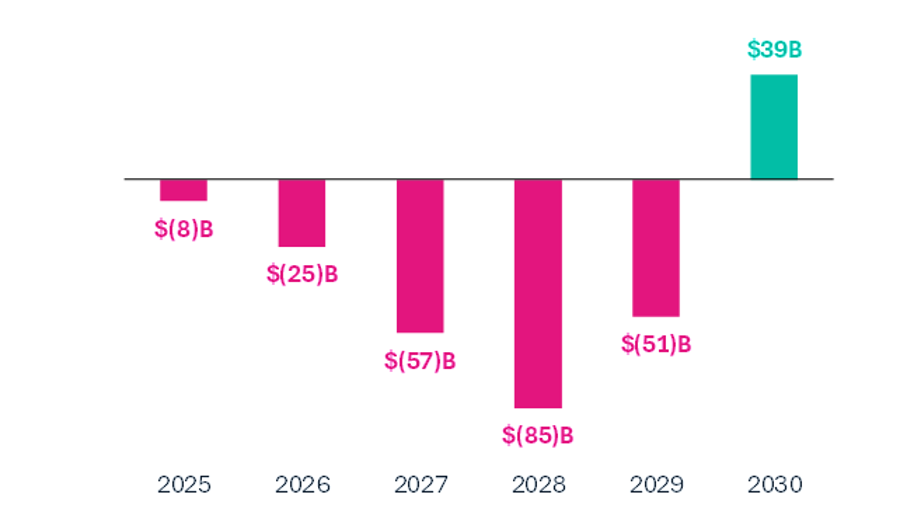
Net cash burn of $25 billion this year. $57 billion in 2027. $85 billion in 2028. $51 billion in 2029. Positive cash flow does not arrive until 2030. If it arrives. Cumulative burn over the next four years: $218 billion. Cumulative compute spending through 2030: $665 billion. HSBC estimated that OpenAI “needs to raise at least $207 billion by 2030 so it can continue to lose money.”
This bears repeating in context.
Before OpenAI, the largest cumulative startup losses in history were Uber's, at roughly $33 billion. OpenAI’s projected losses through 2029 of $218 billion would amount to just over six and a half times Uber’s all-time total.
The Manhattan Project cost about $30 billion in today’s dollars. The Apollo program cost $288 billion over thirteen years. OpenAI projects $665 billion in compute spending (encompassing training and inference costs) in roughly five years, per The Information.
And the forecasts keep deteriorating.
Cumulative cash burn estimates have escalated from $34 billion in Q1 2025 projections to $115 billion by Q3 2025, and now to $218 billion. That’s a $111 billion deterioration in under a year. Gross margins dropped from 40% in 2024 to 33% in 2025, well below the company’s own 46% target, as inference costs quadrupled to $8.4 billion. As a reference point, and despite the difference in business models, successful SaaS businesses maintain margins above 70%.
This is the distinction I keep coming back to. Investors are not financing a technology. They are financing a company.
The technology will persist regardless of what happens to OpenAI’s balance sheet. Open-source models will proliferate (DeepSeek V4 should arrive this week). Anthropic, Google, Meta, and a growing roster of Chinese labs are all building frontier-capable systems. The question is whether the financial architecture constructed around this company can withstand the strain, or whether its eventual restructuring sends shocks through an ecosystem that has become dangerously interconnected.